Refinancing Out of a Maturity Default
The borrower needed to refinance out of an existing bridge loan on a four-family property in Chicago, Illinois.
Timing mattered because the bridge loan was heading into maturity default. Left unresolved, the borrower would have faced extension fees on top of the default itself.
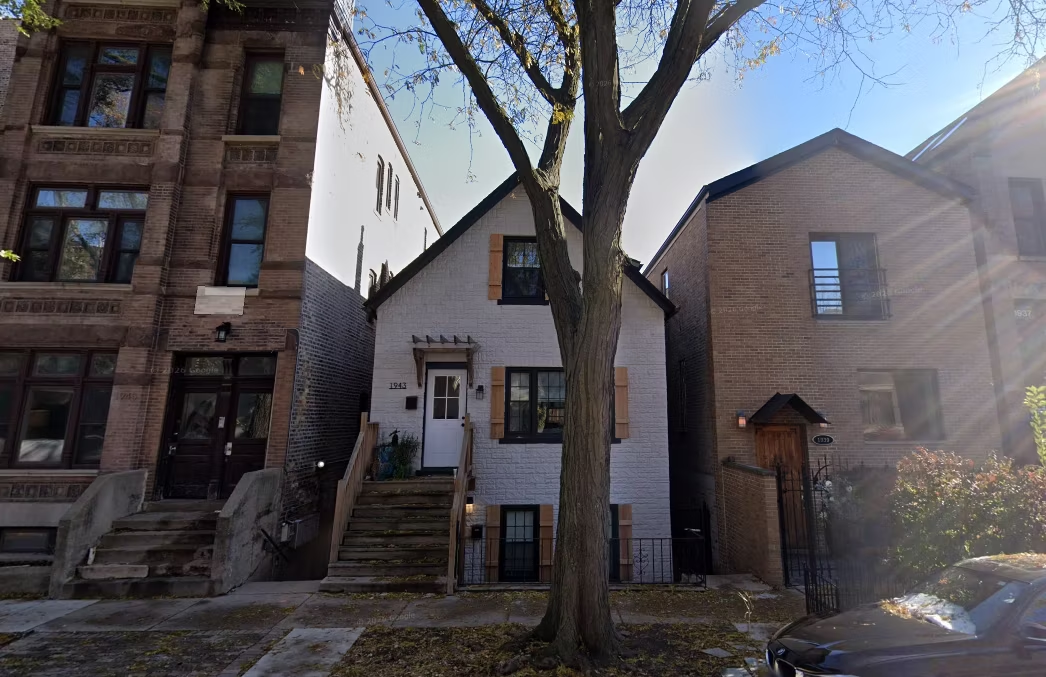
A Legal Nonconforming Four-Family
The property was legal nonconforming. It is grandfathered in as a four-family under Chicago zoning, but the city requires a rebuild letter confirming the property can be rebuilt within one year if it is ever torn down.
The language the city provides in that letter does not clear underwriting with most lenders, which leaves the file stuck indefinitely. Brick City Capital used two legal nonconforming comps from the appraisal report to satisfy underwriting instead of requiring the rebuild letter.
Standard rebuild letter requirement, using city language that does not clear most lenders' underwriting.
Another lender could not complete the appraisal transfer.
Sourced two legal nonconforming comps from the appraisal report to bypass the requirement entirely.
Accepted the appraisal report the broker already had and completed the transfer.
How It Closed in 16 Days
The file moved from intake to closing without waiting on a rebuild letter that would have stalled it indefinitely.
WEEK 1
File Intake and Appraisal Transfer
The broker submitted the file and provided an existing appraisal report. Brick City Capital completed the appraisal transfer after another lender could not.
WEEK 2
Underwriting the Legal Nonconforming Issue
The team identified two legal nonconforming comps on the appraisal report to satisfy underwriting in place of the city's rebuild letter.
DAY 16
Closing
The loan closed as structured, at 75% LTV, on the terms originally quoted.
- Closed in 16 days.
- Closed to the exact structure and terms quoted.
- Borrower refinanced out of the bridge loan before maturity default and avoided extension fees.
Why This Deal Matters
Legal nonconforming multifamily properties are common in cities like Chicago, where zoning is grandfathered rather than current. A rebuild letter requirement tied to that status can leave a file stuck with no clear resolution.
Comparable appraisal data showing similar nonconforming use in the area gives underwriting a path forward without waiting on city language that may never satisfy lender standards.
Time to close on a $1.05M legal nonconforming four-family refinance.

"Just because something doesn't fit a specific box or a check mark, there's still ways to accomplish the goals, make the secondary market happy, make our investors happy, and also the borrower and broker happy."
Who This Deal Speaks To
This file applies directly to a specific set of situations.
- Brokers with borrowers approaching bridge loan maturity. This borrower refinanced out before the loan hit maturity default, avoiding extension fees in the process.
- Investors holding legal nonconforming multifamily properties. A four-family grandfathered into its zoning classification cleared underwriting without a rebuild letter, using comparable appraisal data instead.
- Brokers who already have an appraisal report on file. The existing appraisal was transferred directly rather than ordering a new one, after another lender could not complete the transfer.